

FLCT H2 DPU flat at S$0.0295 despite higher revenue, property income
Manager expects borrowing costs to rise in FY2027, asset valuations to face pressure as bond yields remain elevated
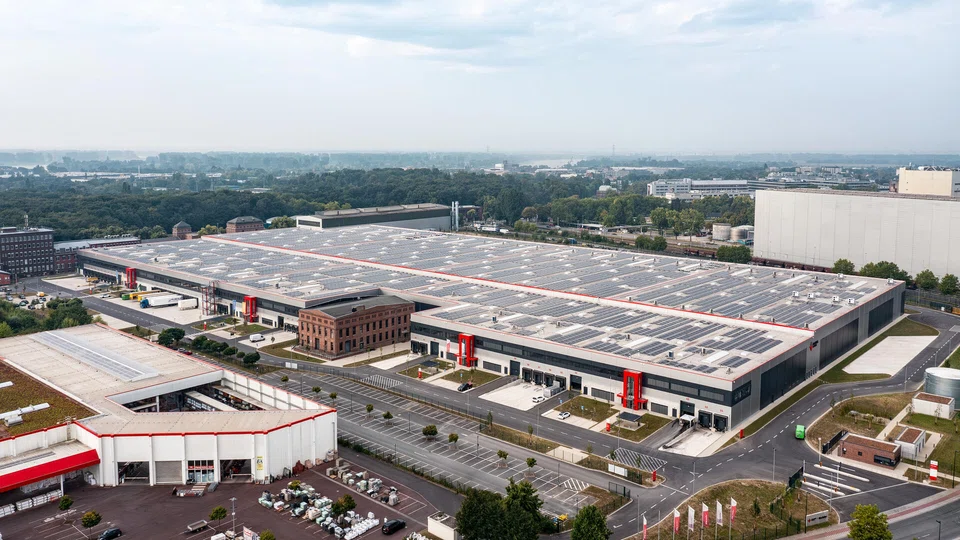
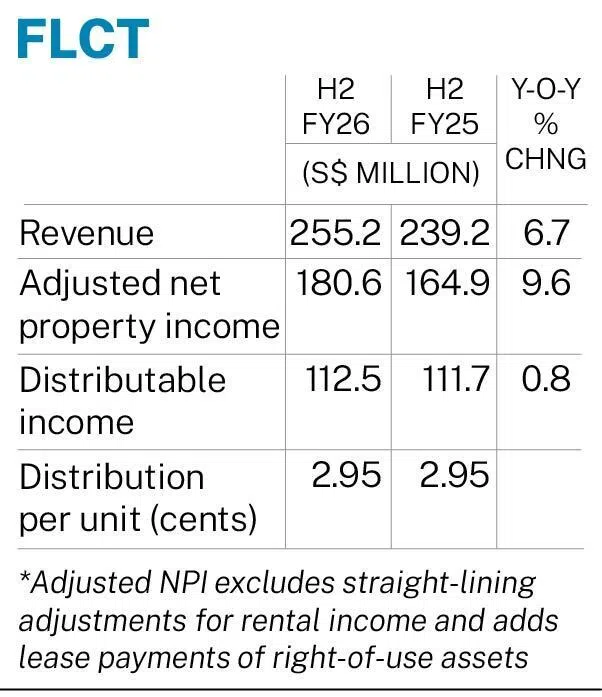
[SINGAPORE] The manager of Frasers Logistics & Commercial Trust ( FLCT ) on Friday (Nov 6) posted a distribution per unit (DPU) of S$0.0295 for the second half ended September, unchanged from the year-ago period.
This represents an annualised distribution yield of 6.7 per cent, based on the annualised DPU and the unit’s closing price of S$0.88 as at Sep 30. The H2 DPU will be paid on Dec 23, after the record date of Nov 19.
Excluding capital distribution of divestment gains, which fell to S$70,000, DPU would have risen 7.1 per cent to S$0.0288 from S$0.0269 previously.
Distributable income for the six-month period edged up 0.8 per cent to S$112.5 million, from S$111.7 million a year earlier. Excluding capital distributions from divestment gains, distributable income increased 7.6 per cent to S$109.5 million, from S$101.8 million a year earlier.
The increase came on the back of lower income tax expenses, but was partially offset by higher finance costs and a lower proportion of management fees paid in units, at 75 per cent compared with 96 per cent previously.
Revenue rose 6.7 per cent on the year to S$255.2 million, while net property income (NPI) grew 8.8 per cent to S$187.6 million.

Adjusted NPI – which excludes straight-lining adjustments for rental income and adds lease payments of right-of-use assets – rose 9.6 per cent year on year to S$180.6 million.
The manager attributed the stronger revenue and NPI to higher annual increments from its logistics and industrial (L&I) portfolio, and higher average exchange rates of the Australian dollar and euro against the Singapore dollar.
Higher occupancy at Alexandra Technopark and contributions from acquisitions of logistics properties in Germany and the Netherlands also lifted performance.
These gains were partially offset by the divestment of 357 Collins Street in September 2025 and higher non-recoverable land taxes in Australia’s Victoria and Queensland states.
Finance costs rose 8.2 per cent to S$47.1 million, mainly due to higher interest rates on refinanced borrowings and additional debt drawn to fund acquisitions.
For the full year ended September, FLCT’s DPU slipped 0.8 per cent to S$0.059 from S$0.0595 a year earlier. Total distributable income was down 0.1 per cent at S$224.4 million, from S$224.7 million previously.
Revenue rose 4.8 per cent on the year to S$494.1 million, while adjusted NPI grew 6.6 per cent to S$347.6 million.
Portfolio performance
As at end-September, FLCT’s overall portfolio occupancy stood at 96.2 per cent, with occupancy for its L&I properties at 99.1 per cent, compared with 89.7 per cent for its commercial properties.
The real estate investment trust (Reit) achieved average rental reversions of 10.4 per cent for FY2026 on an incoming-rent-versus-outgoing-rent basis, while reversions on an average-rent basis stood at 24 per cent.
Its portfolio of 118 properties across five countries was valued at S$7.2 billion, down 2.3 per cent against its carrying value. The decline was mainly due to vacancies, yield softening and weaker European currencies, although positive rental reversions in its L&I portfolio and a stronger Australian dollar helped support valuations.
Commercial properties recorded an 8.7 per cent decline in valuation against carrying value, compared with a 0.4 per cent decline for L&I assets.
Net asset value per unit fell to S$1.07 as at end-September, from S$1.10 a year earlier.
Outlook
The manager expects borrowing costs to rise in FY2027, reflecting higher interest rates on variable-rate borrowings and debt due for refinancing.
“Asset valuations may face pressure as bond yields remain elevated; however, the structural case for prime logistics and industrial assets remains compelling, underpinned by long-term tailwinds such as e-commerce growth, supply chain resilience and nearshoring,” it noted.
As at Sep 30, FLCT’s aggregate leverage stood at 39.2 per cent, with a weighted average debt maturity of 3.1 years and an interest coverage ratio of 4.5 times. Its average cost of borrowing was 3.2 per cent per annum, up from 3.1 per cent a year earlier, while 70.9 per cent of its borrowings were at fixed rates.
The manager added that the ongoing geopolitical and trade uncertainties had not materially affected its operations, occupancy or leasing commitments.
Units of FLCT ended Thursday 1.7 per cent or S$0.015 higher at S$0.925.
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Copyright SPH Media. All rights reserved.
TRENDING NOW
Singapore tech stocks plunge as Nasdaq bloodbath spills into region

S$3 billion money laundering case: Rare Pateks and Rolexes, diamond-covered Hermes and more head to auction

OCBC Q3 profit rises 3% to S$2.04 billion, slightly above expectations

From legacy to launch: Francis Yeoh and Yeoh Pei Xien on family unity and YTL’s next‑gen ventures

