Maybank initiates MoneyMax coverage with ‘buy’ call, S$0.69 target price
The brokerage expects Malaysia expansion and higher-margin pawn loans to drive earnings growth
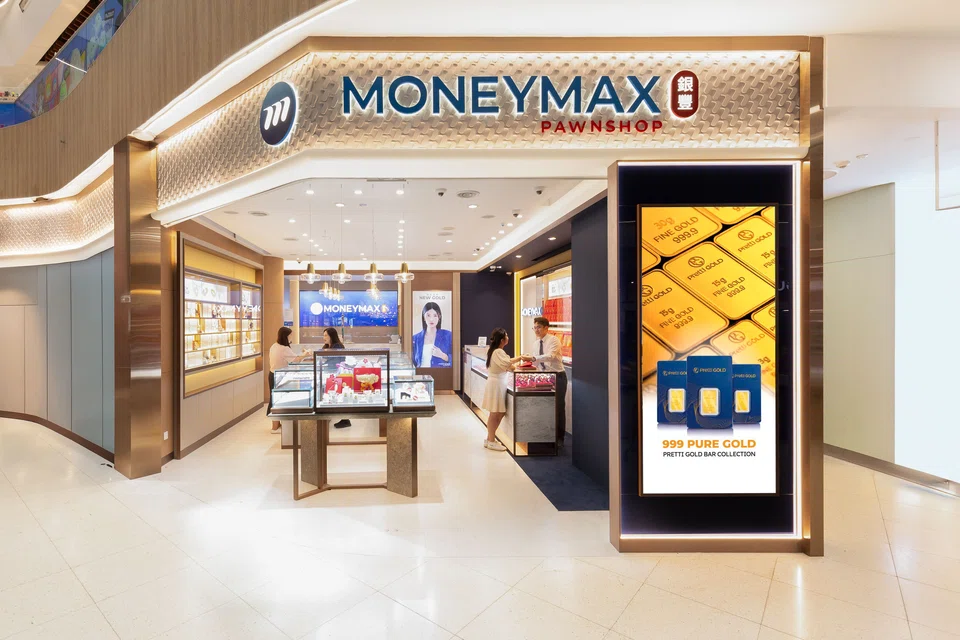
[SINGAPORE] Maybank Research has initiated coverage on MoneyMax Financial Services with a “buy” rating and a target price of S$0.69, representing a potential upside of 38 per cent from the stock’s previous close of S$0.50 on Friday (Nov 6).
In a report on Nov 9, analyst Toh Xuan Hao identified three key growth drivers for the Singapore-listed pawnbroker:
- its expanding Malaysian outlet network,
- a growing portfolio of higher-margin pawn loans, and
- gold retail sales supported by elevated gold prices.
Despite having the highest return on equity among its listed peers, MoneyMax trades at just 4.8 times estimated FY2027 earnings, Maybank noted.
The brokerage’s S$0.69 target price is based on a valuation of 7.9 times estimated FY2027 earnings, in line with the market-capitalisation-weighted average of its peers.
Maybank forecasts MoneyMax’s core net profit to rise from S$72 million in FY2025 to S$103 million in FY2026, before reaching S$112 million in FY2027.
The group reported a 77.3 per cent rise in net profit to S$52.5 million for the first half of 2026, while revenue grew 34.1 per cent to S$325.7 million, driven by its core businesses.

Malaysian expansion
The brokerage highlighted MoneyMax’s expanding physical network as a key competitive advantage, particularly in Malaysia, where the pawnbroking market remains fragmented.
The group operated 139 outlets across Singapore and Malaysia as at H1 2026, up from 113 at end-2025. This meant it added 26 outlets in the first half of 2026 alone, exceeding the 15 opened across 2024 and 2025 combined.
Maybank expects the network to reach 164 outlets by end-2027 and 179 by end-2028.
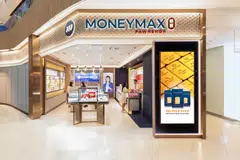
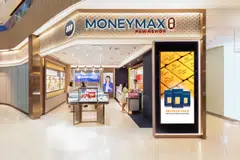
Malaysia is expected to drive much of this expansion. The brokerage forecasts revenue from the country to grow at a compound annual growth rate (CAGR) of 26.1 per cent between FY2025 and FY2028.
It also expects the Malaysian business to contribute about 34 per cent of the group’s pre-tax profit by FY2027.
MoneyMax’s drive-through pawnshop format could strengthen its position in Malaysia, where high car ownership makes the service particularly convenient for customers, Toh noted.
Pawnbroking to drive earnings
Maybank expects pawnbroking to become MoneyMax’s largest profit contributor, driven by its expanding loan book and higher profit margins.
“Demand for short-term, collateralised credit had proven resilient through economic cycles, supported by customers with limited access to bank financing,” said Toh.
Higher gold prices have also increased the value of pledged jewellery and other valuables, allowing customers to obtain larger loans.
The segment’s pre-tax profit margin reached 43.2 per cent in FY2025, more than three times the 12.1 per cent margin recorded by its retail and trading business.
Maybank forecasts pawnbroking revenue to grow at a CAGR of 22.5 per cent between FY2025 and FY2028, reaching S$178.7 million.
By FY2027, the segment is expected to account for about 53 per cent of group pre-tax profit.
Gold retail and trading operations are another growth driver. Higher gold prices have lifted transaction values, while MoneyMax’s shift towards lighter and more affordable jewellery has helped sustain sales volumes.
Maybank expects the segment’s pre-tax profit to grow at a CAGR of 13.3 per cent between FY2025 and FY2028.
However, the brokerage cautioned that a sharp correction in gold prices could reduce collateral values and weigh on pawn loan growth and trading activity.
Other risks include tighter pawnbroking regulations and operational lapses, which could affect profitability and customer confidence.
Decoding Asia newsletter: your guide to navigating Asia in a new global order. Sign up here to get Decoding Asia newsletter. Delivered to your inbox. Free.
Copyright SPH Media. All rights reserved.